A retirement planning institute offers structured, group-based education on 401(k) strategy, investment basics, and income planning for a fraction of what you’d pay a traditional advisor. Many programs now deliver comprehensive retirement coursework for around $75 across several sessions, putting professional-level guidance within reach of small business owners who need to make confident decisions about their own retirement accounts and employee benefits without burning through cash reserves on high-fee consultations.
For entrepreneurs, the 401(k) sits at the intersection of personal wealth-building and business responsibility. You’re weighing contribution levels that affect your take-home pay, evaluating plan designs that attract and retain talent, and trying to decipher IRS rules that shift annually. Most founders lack the bandwidth to become retirement experts, yet hiring a financial planner often costs thousands for ongoing service contracts. That’s where the institute model shines: you get expert instruction, peer discussion, and a framework for your decisions in a classroom format that fits a realistic budget and schedule.
The typical retirement planning institute curriculum covers contribution strategies, asset allocation for different life stages, employer match structures, tax-advantaged investing, and how to coordinate 401(k) savings with other retirement vehicles. You’ll walk out with practical tools to benchmark your own plan against industry norms, spot fee drag that erodes returns, and communicate retirement benefits clearly to employees. This approach won’t replace personalized financial planning for complex estates or specialized tax situations, but it delivers the core knowledge most small business owners need to make smart 401(k) choices today and adjust course as their companies grow.
What Retirement Planning Institutes Offer Small Business Owners
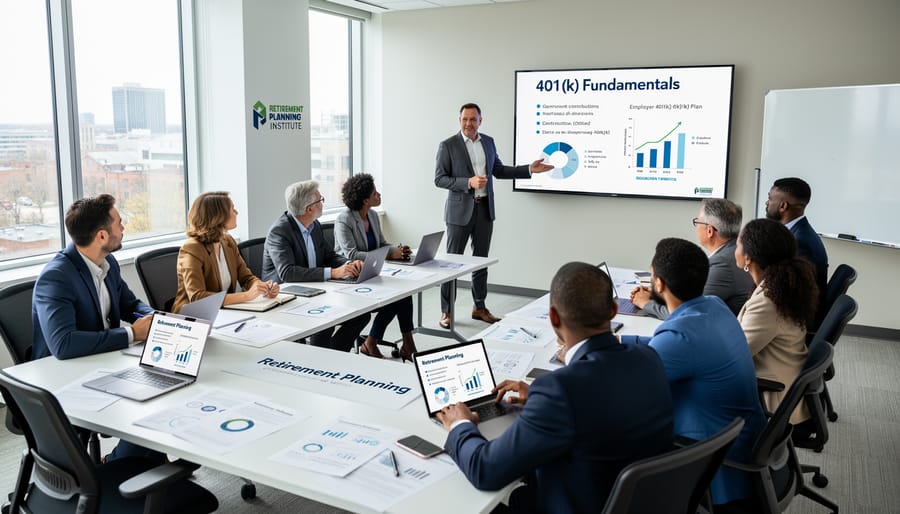
Retirement planning institutes take a fundamentally different approach than sitting down with financial consultants for personalized advice. Instead of one-on-one sessions tailored to your specific portfolio, these educational programs offer structured group courses that teach core retirement planning concepts you can apply to your own situation. Think of them as adult education workshops focused on financial literacy rather than customized financial planning services.
The curriculum typically breaks down complex retirement topics into digestible modules. You’ll work through retirement planning fundamentals that cover the basics of how different retirement accounts function, income strategies that explain how to generate sustainable cash flow in retirement, and investing basics that demystify asset allocation and risk management. These programs assume you’re starting without extensive financial knowledge and build from there, making them particularly useful for entrepreneurs who have focused their expertise on running a business rather than managing investments.
The format varies but often includes a combination of lecture, discussion, and practical exercises where you apply concepts to hypothetical scenarios. Unlike a meeting with an advisor who tells you what to do with your money, these institutes teach you how to evaluate options and make informed decisions yourself. You’re not walking away with a personalized financial plan, but you are gaining the knowledge to create one or to ask much smarter questions when you do eventually work with professionals.
This educational model fills a specific gap for small business owners who need to understand retirement planning mechanics before committing to expensive ongoing advisory relationships. You learn the vocabulary, the trade-offs between different strategies, and the questions you should be asking about your own situation. The structured approach also means you can’t skip ahead to advanced tactics without understanding the foundations, which prevents costly misunderstandings down the road.
The Dual Challenge: Running a Business While Planning Your Own Retirement
Running a business demands constant attention to cash flow, operations, and growth. Add personal retirement planning to that list, and many small business owners find themselves stretched impossibly thin. Unlike employees who can set a payroll deduction and trust their employer’s plan choices, entrepreneurs face decisions on both sides of the equation.
When you’re managing a business, your income rarely arrives in neat bi-weekly paychecks. You might have a strong quarter followed by two lean months. Traditional retirement planning advice assumes steady earnings and focuses on percentage-based contribution strategies that don’t account for this volatility. That cookie-cutter approach falls apart when your income swings wildly or when a significant portion of your net worth sits locked in business equity rather than liquid savings.
If you’ve brought on employees, the complexity multiplies. You’re suddenly responsible for selecting a plan that balances affordability with competitive benefits, understanding fiduciary duties, and handling administrative requirements that consume hours you don’t have. Meanwhile, your own retirement savings often take a back seat to payroll, inventory, and keeping the lights on.
This is precisely where structured education through retirement planning institutes offers practical value. Rather than expensive one-on-one advisory sessions that may not address entrepreneurial realities, these programs teach you how to navigate retirement decisions within your specific constraints. You learn to build flexibility into your planning, understand which plan structures work for businesses at different stages, and develop strategies that account for irregular income patterns. The education empowers you to make informed choices without requiring a finance degree or hours of research you can’t spare.
Understanding 401(k) Options for Your Business
When a Solo 401(k) Makes Sense
A solo 401(k) deserves serious consideration if you’re the only person on payroll, whether you’re a consultant, freelance designer, contractor, or side-hustle entrepreneur with no W-2 employees. The structure lets you contribute as both employer and employee, which often translates to higher total savings than you’d achieve with a SEP-IRA or SIMPLE plan at comparable income levels.
The real advantage shows up when your business generates steady profit but you want maximum tax-deferred room without the administrative complexity of a traditional small-business plan. You’ll handle the paperwork yourself or with minimal third-party help, which keeps costs low. Most custodians charge modest annual fees, and you avoid the compliance burden that comes with covering staff.
That said, solo 401(k) plans lose eligibility the moment you hire someone who works more than 1,000 hours per year, excluding your spouse. If growth means bringing on employees soon, you’ll need to transition to a different plan type. Retirement planning institutes often walk through these eligibility thresholds in their structured courses, helping you map current business realities against future staffing plans so you choose a structure that won’t require an expensive overhaul in two years.
Adding Employees to the Equation
Once you bring on employees, your retirement planning responsibilities multiply. A 401(k) with employees introduces matching contribution decisions, administrative oversight, and compliance obligations that solo plans never require. You are no longer simply saving for your own future, you are managing a benefit program that affects your team and your business budget.
Employer contributions become a key consideration. While some plan types require mandatory matches, others make matching optional. The structure you choose affects both your costs and your ability to attract talent. Many small business owners underestimate the ongoing administrative work: annual testing requirements, participant notices, provider coordination, and year-end reporting all demand attention you may not have anticipated.
This is where structured retirement education proves valuable. Understanding these complexities before you commit to a plan structure helps you avoid costly missteps. Programs that cover employer responsibilities alongside personal retirement strategy give you the full picture, not just what you can contribute, but what you will need to manage once employees join your plan. The right education prepares you to evaluate these trade-offs realistically rather than discovering them after you have already signed provider contracts.
What to Look for in Retirement Planning Education
Not all retirement education programs deliver the same value, and as a busy small business owner, you can’t afford to waste time on courses that don’t translate into real-world decisions. When evaluating retirement planning institutes or similar programs, start with the curriculum. Quality education should move beyond generic investing theory to address the specific challenges you face, including how to structure retirement savings when income fluctuates, balancing business reinvestment with personal financial planning and navigating the practical mechanics of setting up and managing 401(k) plans.
Look for programs that cover:
- Retirement account types and their tax implications for business owners
- Contribution strategies that adapt to variable income
- Employer plan options and fiduciary responsibilities
- Integration with other savings vehicles like IRAs and taxable accounts
- Real cost analysis of different plan structures
Instructor credentials matter, but practical experience often counts more than alphabet soup after someone’s name. Seek out teachers who’ve worked directly with small businesses or who run their own companies, not just those with academic backgrounds in finance. The best programs incorporate case studies, worksheets, and decision frameworks you can apply immediately.
Format depends on your schedule and learning style. In-person sessions foster direct interaction and networking with other business owners facing similar challenges, while online courses offer flexibility. Programs priced around $75 for multiple sessions, like some current retirement planning institutes, provide accessible entry points without the commitment of ongoing advisory fees.
Before enrolling, ask whether the curriculum addresses business owner scenarios specifically, whether you’ll leave with actionable next steps rather than just information, and whether the program includes tools or resources you can reference later. Theory has its place, but you need education that helps you make actual decisions about your retirement accounts this quarter, not someday.
Real-World Application: Turning Education Into Action
Learning about 401(k) plans through a retirement planning institute is valuable, but the real payoff comes when you translate that knowledge into decisions for your business. Start by identifying your immediate next step. If you’re a sole proprietor who just learned about solo 401(k) advantages in a $75 workshop, your action might be requesting quotes from three providers within the next week. If you run a ten-person team and the institute training clarified safe harbor options, schedule a meeting with your payroll company to discuss implementation timelines.
One graphic designer who completed a retirement planning course used the structured framework to finally tackle a decision she’d postponed for two years. The institute’s income module helped her calculate what percentage of fluctuating quarterly revenue she could consistently commit to retirement. She set up automatic transfers of 15% from her business checking to her solo 401(k) provider each month, adjusting quarterly based on actual cash flow rather than making sporadic contributions when she remembered.
Working with providers becomes less intimidating after institute training because you understand what questions to ask. You’ll know to compare administrative fees, investment options, and whether the provider offers business owner-specific guidance. You can evaluate whether their platform lets you adjust contributions easily during lean months.
The education also clarifies when to bring in additional help. A restaurant owner realized through his course that while he could handle the basics of his solo 401(k), hiring seasonal staff next year would trigger compliance requirements beyond the scope of general retirement education. He budgeted for a benefits consultant before expanding his team, avoiding costly mistakes.
Apply what you learned methodically. Choose one concept from the institute curriculum, implement it this month, then move to the next. That might mean setting up payroll deductions, reviewing your current investment allocations, or calculating how different contribution levels affect your tax situation. Education without implementation leaves money on the table.
Beyond the Basics: Building a Comprehensive Retirement Strategy
Your 401(k) represents one piece of a larger financial puzzle. Small business owners who complete retirement planning programs quickly realize that comprehensive retirement security requires thinking beyond a single account type.
Start by examining how your business itself fits into your strategic planning. Many entrepreneurs hold significant wealth in their companies, yet lack concrete succession plans. Will you sell the business to fund retirement? Transfer it to family members? Wind it down gradually? These decisions directly impact how aggressively you fund personal retirement accounts today. A business owner planning to sell in a decade might maintain lower 401(k) contributions now, while someone without business sale prospects needs robust retirement savings outside the company.
Diversification matters more for business owners than traditional employees. Your income, daily focus, and often personal guarantees already tie you heavily to one enterprise. Retirement accounts offer a chance to build wealth in uncorrelated assets. Look beyond employer plans to individual retirement accounts, taxable brokerage accounts, and even real estate investments that provide income streams independent of your business performance.
Tax optimization becomes increasingly complex as you balance business deductions, personal contributions, and income timing. Should you maximize pre-tax 401(k) contributions this year or prioritize Roth accounts? Does your business structure allow for additional tax-advantaged vehicles? Programs like retirement planning institutes provide frameworks for these questions, but ongoing education remains essential. Tax laws shift, business circumstances evolve, and your retirement timeline shortens each year.
The most successful small business owners treat retirement planning as continuous learning rather than a one-time event. Use structured programs as foundations, then commit to annual reviews of your broader strategy as both business and personal finances change.
The gap between knowing you should plan for retirement and actually doing it often comes down to structure and accountability. For small business owners juggling daily operations, structured retirement education programs offer a focused path through complexity without the open-ended time commitment of traditional advising. Programs like retirement planning institutes compress essential knowledge into accessible formats, helping you make informed 401(k) decisions alongside peers facing similar challenges.
The value isn’t just in the information itself but in the clarity it creates. Understanding how different plan structures work, what questions to ask providers, and how to balance business cash flow with retirement contributions transforms abstract anxiety into concrete next steps. You don’t need to become a financial expert to make sound decisions for your business and your future.
The choices you make today about retirement planning create the foundation for both business stability and personal security down the line. Whether you engage with a formal institute program, pursue structured online education, or simply commit to dedicated learning time, the key is taking that first step. Your business demands immediate attention every day, but your retirement timeline doesn’t pause while you figure things out. Start building that knowledge now, even in small increments, and you’ll thank yourself later.